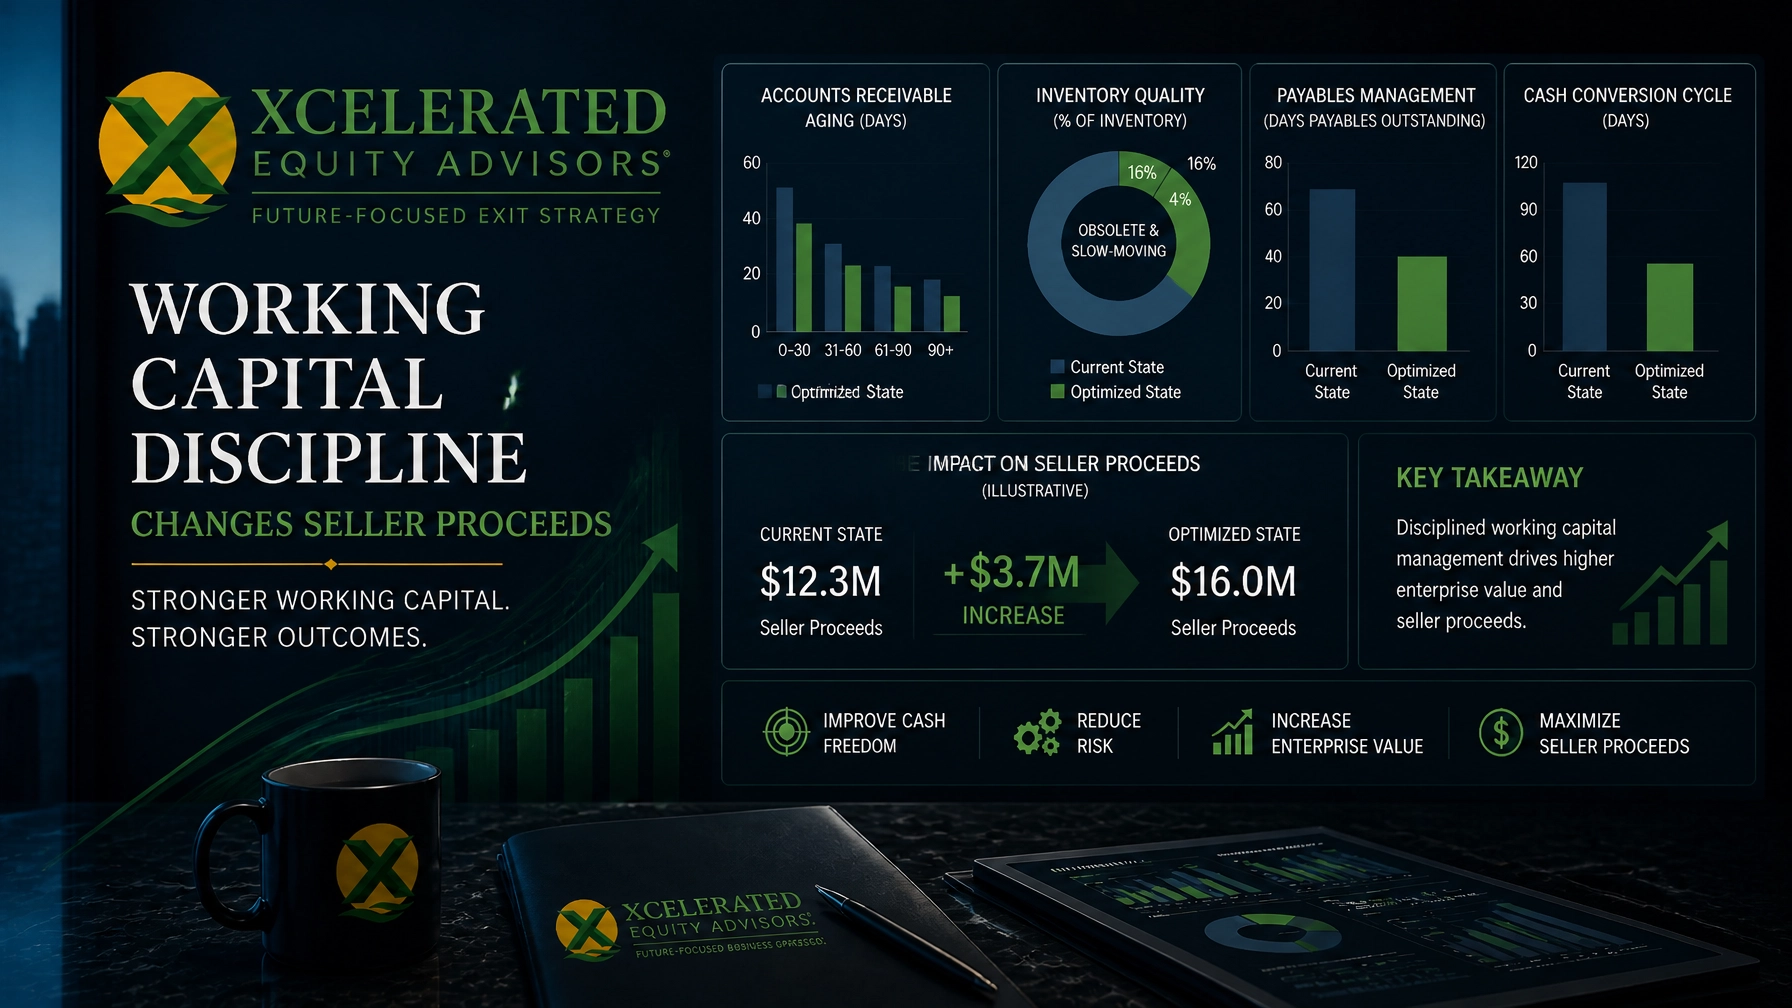

Your working capital discipline changes seller proceeds. EBITDA drives the headline price. The balance sheet determines how much cash you keep at close.
Buyers expect a normal level of net working capital to stay in the business on Day 1. When receivables are slow, inventory is stale, or payables are stretched, they treat the shortfall as a purchase-price issue.
Managing accounts receivable, inventory, and payables is a direct lever for increasing enterprise value BEFORE a transaction, not during one.
The Hidden Mechanics of the Working Capital Peg
The "peg" is the net working capital target you must deliver at closing. Buyers usually set it from a 12-month average of operating working capital. If actual working capital comes in below that target, the purchase price is reduced dollar-for-dollar.
Buyers test the history behind that number. If collections spike before closing or vendor payments slow down, they treat the change as temporary and normalize it out. That can push the peg higher and force more cash to stay in the business.
Exit-Ready Financials & KPIs give you a clean history to defend the peg. That matters when a buyer is deciding whether your working-capital profile reflects normal operations or a short-term clean-up.
1. Accounts Receivable: The Trap of Aging Debt
A receivables ledger with a meaningful share beyond 60 or 90 days signals collection risk. Buyers often exclude aged AR from the working-capital calculation while still holding you to the full peg.
That creates a direct purchase-price issue. If those receivables do not count, you replace the gap with cash at closing. The result is a dollar-for-dollar reduction in proceeds tied to work already performed.

2. Inventory: The Weight of Bloated Stock
High inventory levels, excess safety stock, and obsolete items tie up cash and weaken cash conversion. Buyers separate current inventory from slow-moving or obsolete stock when they assess working capital.
If they discount those categories or set a higher normal inventory level in the peg, more cash stays trapped in the business. That creates a drag on enterprise value and lowers proceeds because you do not get full credit for dollars already spent on noncurrent stock.
3. The Working Capital Peg: The Second Negotiation
Wide swings in working capital from uneven billing cycles or poorly managed payables give buyers room to challenge your baseline. They can argue for a peg based on peak periods instead of a normalized average.
If actual working capital misses that inflated peg, the shortfall comes off the purchase price dollar-for-dollar. Failing to manage these metrics in the 12–72 month window before a buyer is involved means you are likely to lose 5% to 15% of your deal value to technical adjustments.
Optimizing for the Final Payout
Working capital discipline affects proceeds through specific buyer actions. Tight collections reduce AR aging. Cleaner inventory reduces obsolete stock. Controlled payables create a more stable cash conversion pattern. Value Growth Sprints help address those conditions before diligence starts.
Buyer-ready financials also matter in the peg negotiation. When you can show stable working-capital needs with clean support, buyers have less room to recast the target or challenge what belongs in the calculation.
This is where sellers either preserve proceeds or give them up through avoidable balance-sheet adjustments.
Start with the assessment here: https://xeadvisors.com/exit-assessment/ This will identify where value is lost before a transaction.