
Most owners treat customer concentration as a math problem. They calculate the percentage of revenue tied to the largest accounts and assume the risk rises or falls with that number.
That calculation matters, but it does not tell a buyer whether the revenue will survive a change in ownership.
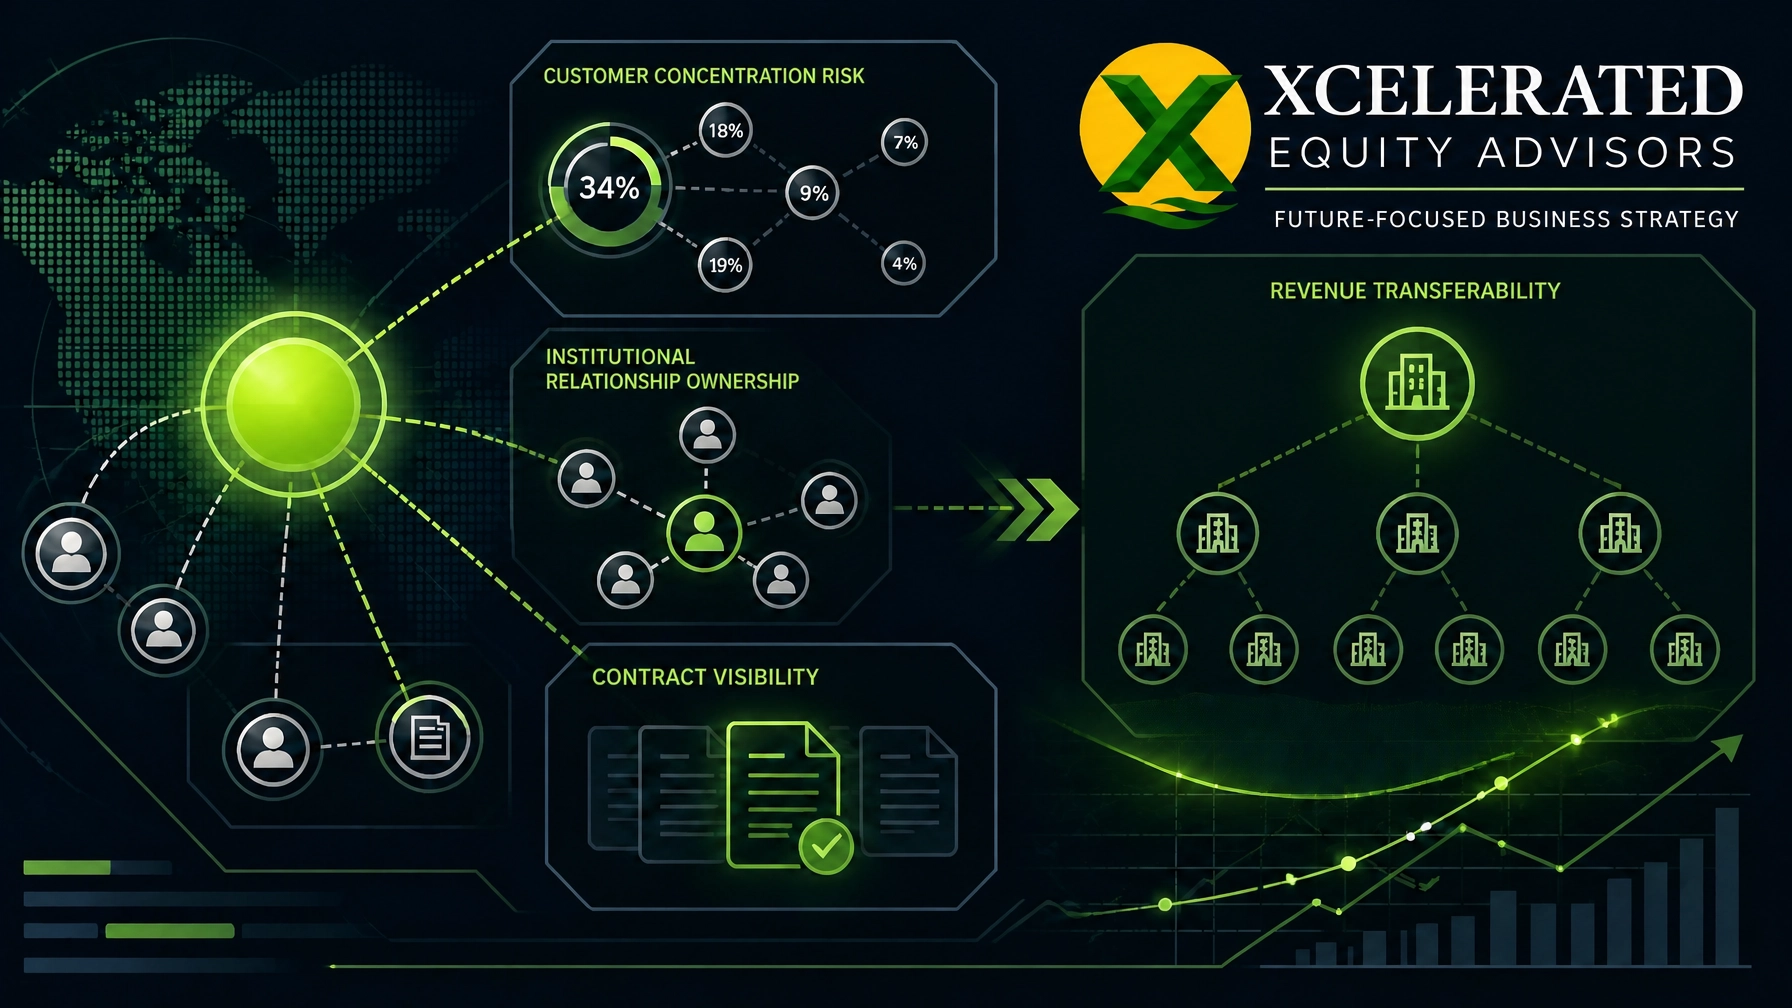
Consider two businesses that each generate 30 percent of revenue from one customer. In the first business, the account is covered by a written agreement, managed by an experienced executive, supported by several customer relationships, and served through documented operating processes. In the second, the founder won the account, handles every renewal, resolves every service issue, and keeps the relationship history in personal emails and memory.
The reported concentration is identical. The transferability of the revenue is not.
A buyer will evaluate both the amount of revenue at risk and the company’s ability to retain, deliver, and replace it. That broader analysis can affect valuation, the amount paid at closing, the seller’s required transition period, and whether the buyer proceeds at all.
The Percentage Is Only the Starting Point
A useful concentration analysis goes beyond a list of customers ranked by revenue. It should show how exposure has changed over several years and where the economic dependence actually sits.
For each material customer, review:
- Revenue and gross profit contribution.
- Accounts receivable exposure and payment history.
- Contract term, renewal date, and termination rights.
- Revenue by location, division, or operating unit.
- Customer-specific staffing, equipment, or service requirements.
- The employees who own the relationship and deliver the work.
- The strength of the replacement pipeline.
Revenue alone can understate the problem. A customer responsible for 15 percent of revenue may represent a much larger share of gross profit. Another customer may dominate one location even though its company-wide percentage appears manageable. A large outstanding receivable can also create a cash-flow exposure that does not appear in a revenue report.
This is why a consolidated percentage can provide false comfort. Buyers examine where the concentration affects earnings, cash flow, operating capacity, and individual business units.
Buyers Underwrite Four Forms of Dependence
Customer concentration becomes more serious when it overlaps with other forms of dependence.
Economic dependence
The loss of a major account may reduce more than revenue. It can leave dedicated employees, facilities, inventory, or equipment without enough work to support the existing cost structure. The buyer will assess how quickly expenses can be adjusted and how much EBITDA would remain if the account were lost.
Contractual dependence
A written contract does not make revenue secure by itself. Termination-for-convenience provisions, short renewal cycles, assignment restrictions, pricing resets, and weak minimum commitments can leave the customer with substantial flexibility.
The contract register should make those terms visible before diligence begins. If management needs to search email chains to explain a major account, the buyer will assume there are additional gaps.
Relationship dependence
The central issue is who owns the relationship. An account managed across sales, operations, finance, and senior leadership is more durable than one tied to the founder or a single employee.
Founder access can help win and retain important customers. It becomes a valuation problem when no one else understands the account, holds decision-maker relationships, or has authority to resolve issues. At that point, the buyer is acquiring revenue without clear evidence that the commercial relationship will transfer.
This is one reason the leadership gap affects buyer pricing. Xcelerated Equity Advisors’ leadership gap analysis explains how concentrated authority can weaken the value of otherwise strong earnings.
Operational dependence
Customer retention depends on delivery. A long-standing relationship can still be fragile when the company relies on undocumented exceptions, owner intervention, or a few long-tenured employees to fulfill its promises.
The buyer needs to understand how the work is performed, how service failures are handled, and whether the operating team can maintain quality after the owner steps back. Documented procedures, customer-level performance measures, clear escalation paths, and accountable managers provide better evidence than assurances about loyalty.
Renewal History Is Evidence, but It Is Not a Guarantee
Owners often defend a concentrated account by pointing to a long relationship. Tenure is useful evidence, but it does not eliminate forward-looking risk.
Procurement leadership changes. Budgets tighten. Competitors improve. A customer acquired by another company may consolidate vendors. A relationship that lasted 15 years can still change shortly after a transaction.
A credible renewal file should combine history with current evidence. It should include the agreement, renewal calendar, account health, service performance, open issues, pricing discussions, customer contacts, and recent communications. Management should distinguish committed revenue from expected renewals and active sales opportunities.
Blending those categories into one forecast makes the business appear less disciplined. Clear separation gives the buyer a more reliable basis for evaluating future earnings.
Concentration Changes Deal Structure
When a buyer cannot establish that a major account will transfer, the response is not limited to a lower valuation multiple. The buyer may also:
- Condition part of the purchase price on customer retention.
- Require a longer seller transition period.
- Seek customer consent or confirmation before closing.
- Reduce the cash paid at closing.
- Walk away if the account is essential to the investment thesis.
An earn-out tied to customer retention does not repair the risk. It shifts part of the risk back to the seller. Owners who wait until diligence to address concentration usually negotiate after the buyer has already identified the weakness and framed the solution.
The stronger position is to address the evidence and operating gaps before the sale process begins.
What an Owner Can Change Before a Sale
Customer mix may take years to change. The risk surrounding that mix can often be reduced sooner.
Produce a customer concentration report that covers revenue, gross profit, receivables, contract status, location exposure, and relationship ownership. Review it quarterly with the leadership team.
Transfer account knowledge and authority. Assign a primary account leader and an executive sponsor. Build relationships with several contacts inside the customer, including operating, financial, procurement, and executive stakeholders. Document customer objectives, service commitments, pricing history, open risks, and renewal actions in a shared system.
Prove that delivery does not depend on the owner. Standardize customer-specific work, define escalation authority, track service performance, and make managers responsible for resolving issues. Founder involvement can continue while account ownership is spread across the management team. The company must be able to retain and serve the customer without relying on the founder as its operating system.
Build credible replacement capacity. A sales pipeline does not erase existing concentration, but it shows whether the company has a repeatable way to replace lost revenue. Buyers will distinguish between a documented pipeline with defined stages and a list of names management hopes to convert.
Make the Evidence Easy to Verify
The work is incomplete if the supporting information cannot be found during diligence. Customer contracts, amendments, renewal records, account plans, concentration reports, service metrics, and relationship maps should be current and organized.
This is where operational readiness and deal readiness meet. A disciplined data room does more than make document review convenient. It shows that management understands its obligations and controls the information used to run the business. The XEA data room indexing framework explains why document quality can influence a buyer’s view of operational quality.
Customer concentration cannot always be eliminated before a transaction. It can be measured accurately, governed deliberately, and supported with evidence.
The buyer is deciding whether the earnings belong to the enterprise or depend on relationships and knowledge that may leave with the owner. Businesses that can prove institutional ownership of their customers enter that discussion with more credibility and greater negotiating leverage.
Start with the assessment here: https://xeadvisors.com/exit-assessment/ This will identify where value is lost before a transaction.