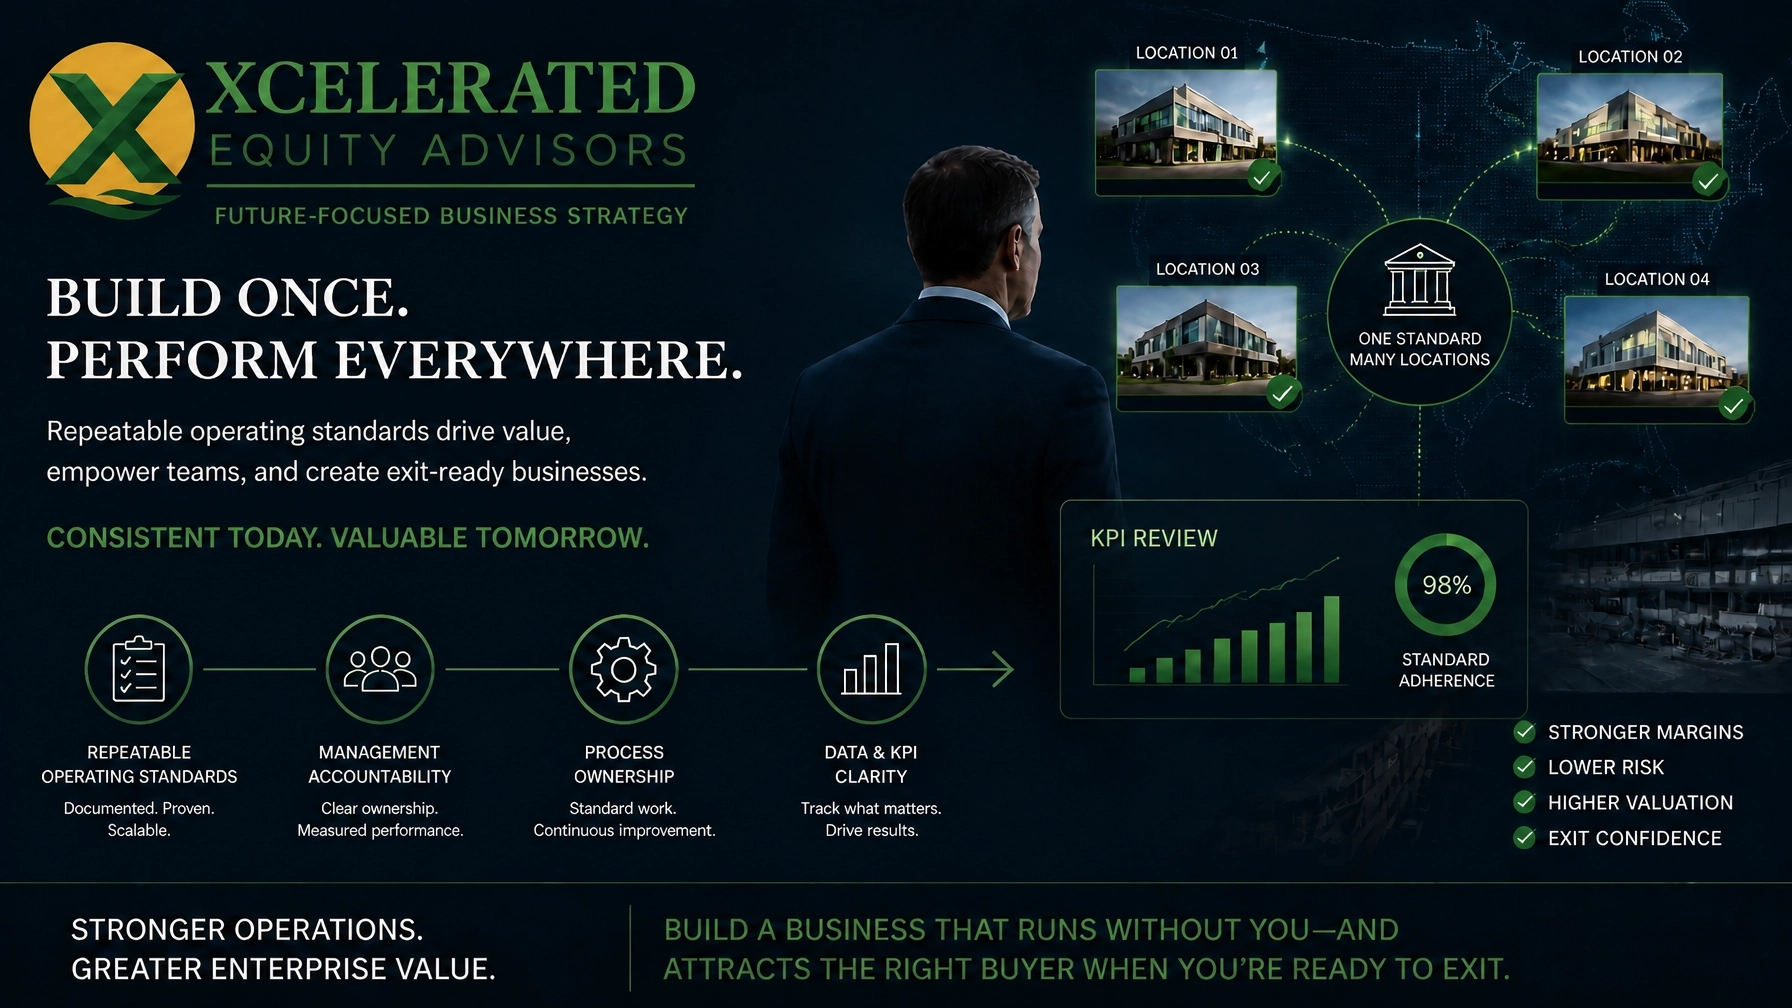

Two locations can report the same margin and still represent different levels of business quality. One produces the result through trained managers, defined standards, and routine performance review. The other reaches the number because the owner intervenes whenever performance slips. The financial result is the same. The transferability of that result is not.
The Same Margin Can Hide Different Businesses
A location-level P&L can show acceptable labor, margin, and revenue performance while saying very little about how the result was produced. One business may be operating through manager discipline and clear controls. Another may be relying on constant owner involvement, verbal correction, and a set of informal workarounds that never appear in the reporting package.
That distinction matters because buyers do not evaluate financial output in isolation. They test whether the operating result can survive a change in leadership. If the business depends on one person stepping in to approve exceptions, resolve customer issues, or correct execution drift, the reported performance has less transfer value.
The same logic applies to consolidated results. Strong company performance can mask uneven execution across units, weak management depth, or a pattern where one experienced person keeps the system together. Buyers look below the summary numbers because operating quality determines whether historical results can be repeated.
An SOP Is Only the Starting Point
Many owners assume repeatability exists once procedures are written down. That is incomplete. A documented procedure is not a repeatable operating system. Repeatability requires a defined standard, a named process owner, a performance measure, rules for handling exceptions, and evidence that another manager can produce the result.
The defined standard tells the team what good execution looks like. The process owner is the manager accountable for keeping the standard current, training the team, reviewing the performance measure, and addressing exceptions. The performance measure shows whether the process is producing the intended result. Exception rules prevent the system from collapsing the first time reality does not follow the script. Proof from another manager shows the process belongs to the business rather than to one individual.
Without those elements, the SOP often becomes reference material instead of an operating tool. It may sit in a binder or shared drive while day-to-day decisions continue to depend on memory, instinct, or the owner's judgment.
How Buyers Test Repeatability
There is no single buyer test for repeatability. Buyers compare performance across managers, locations, and time to see whether the business behaves consistently under normal operating pressure.
They review onboarding to understand how a new manager learns the system and how quickly that person can take responsibility without owner intervention. They look at KPI definitions to see whether units are measuring the same things in the same way. They study variance response to determine whether missed targets trigger a routine management process or a call to the owner.
Routine decisions reveal a great deal. Pricing exceptions, staffing adjustments, customer recovery, and service escalation all show whether authority has been transferred into the business. When those decisions can be made inside the management structure, repeatability is easier to prove.
The related XEA article on Data Room Indexing as a Proxy for Operational Quality shows how organized evidence can support a buyer’s review of operational control.
Transfer Three Critical Processes
Start with three processes that directly affect revenue, service quality, margin, or control. Choose processes that matter enough to expose whether the business can operate without owner rescue. Examples may include scheduling, customer escalation, pricing approval, inventory control, or unit-level reporting.
For each process, assign one manager to own execution. Document the operating standard in plain language. Define the measure that shows whether the process is working. Record exceptions so the business can see where the process breaks and why.
Then test the process without owner intervention. Let the assigned manager run it through normal conditions, including the exceptions that usually trigger escalation. Retain the evidence. Keep the written standard, the process ownership assignment, the KPI result, the exception log, and the record of what happened when another manager ran the process. That package gives a buyer something concrete to evaluate.
What This Changes for the Owner
Repeatability reduces owner dependence because routine operating decisions move into the management team. It also strengthens management depth by making performance less dependent on one experienced person holding the system together. It reduces the owner’s routine involvement, creates room to focus on higher-value decisions, and makes it possible to step away without performance immediately depending on the owner.
That shift changes the quality of the discussion with a buyer. The buyer can evaluate future performance with less guesswork because the business has shown how results are produced, who owns the process, and how the system responds when performance moves off standard.
Repeatability improves quality of earnings because it gives a buyer evidence that performance can continue under new ownership. The business becomes easier to manage, easier to scale, and less dependent on the owner. Those improvements create value long before a transaction begins.

Use the XEA Exit Assessment to identify where owner dependence, inconsistent execution, and weak management systems are limiting transferability and enterprise value.